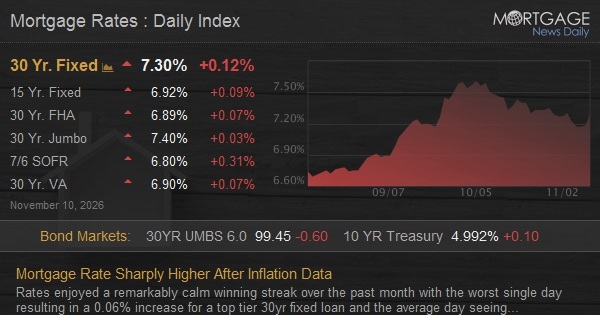
Rates enjoyed a remarkably calm winning streak over the past month with the worst single day resulting in a 0.06% increase for a top tier 30yr fixed loan and the average day seeing a 0.02% decline. That streak was dealt its first serious blow today following a hotter than expected in the Consumer Price Index (CPI)--a key inflation report.
Even though the Fed's official inflation target is based on Personal Consumption Expenditures (PCE), we'll be waiting another 2 weeks for that report to come out for the month of October. CPI (the one we got today) always comes out earlier in the month and because much of the data flows through to the more robust PCE data set, CPI reliably produces more volatility for the bond/rate market.
Today's report showed broad-based price pressures with only a small handful of categories seeing any improvements. Naturally, the categories most closely tied to higher fuel prices were the worst, but many non-fuel-related categories were surprisingly high.
Given that the Fed explicitly said it was more focused on the inflation component of its job description at the moment (as opposed to the "full employment" component), we were expecting today's data to carry far more weight than last week's jobs report. The reaction was logical an immediate. When the dust settled, the average top tier 30yr fixed rate was 0.12% higher day over day at 7.30%.
While that's the largest one day increase in over a month, it's still quite a bit lower than the 7.6%+ levels seen in early October.
 Follow Mortgage Rate Watch daily in our email newsletter.