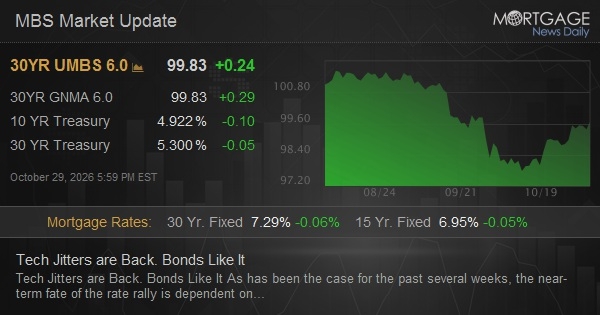
As has been the case for the past several weeks, the near-term fate of the rate rally is dependent on tech jitters. While those had leveled off in a sideways pattern over the first few days of the week, they resurfaced today, both at the NYSE open and close. The 4pm move was bigger for stocks and directly linked to weak guidance in Intel and Amazon earnings releases. Bonds were already moderately stronger on the day after the 9:30am gains, but improved even more after the 4pm NYSE close.
Econ Data / Events
-
- Core PCE (m/m) (Sep)
- 0.3% vs 0.3% f'cast, 0.2% prev
- Core PCE (y/y) (Sep)
- 3.1% vs 3.1% f'cast, 3% prev
- GDPQ3
- 3.4% vs 3.2% f'cast, 2.2% prev
- Jobless Claims (Oct)/24
- 194.0K vs 199K f'cast, 194K prev
- Core PCE (m/m) (Sep)
Market Movement Recap
09:55 AM
fairly sharp rally at 9:30am coincided with NYSE open and heavy losses in a few key tech names


 MBS Market Alerts