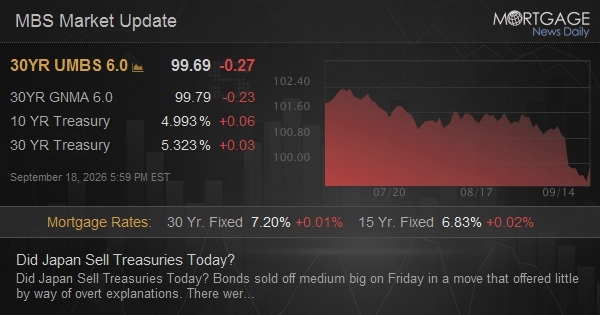
Bonds sold off medium big on Friday in a move that offered little by way of overt explanations. There were reports of "rate checks" in the USD/JPY market--something that CAN precede the selling of U.S. bonds in order to buy JPY. Notably, there were no reports of actual intervention, but sometimes these things aren't revealed until the following trading day. If this explains today's weakness (and to be clear, we're not sure it does), it would be good for the U.S. bond market as it would mean 10yr yields still held under 5% despite added, artificial pressure. Causality investigations aside, we'd focus on the fact that 10yr yields held under 5% (albeit just barely), which is right where they were on the Tuesday afternoon before Fed day.
-
- Building Permits (Aug)
- 1.394M vs 1.41M f'cast, 1.433M prev
- Continued Claims (Sep)/05
- 1730.0K vs 1780K f'cast, 1774K prev
- Housing starts number mm (Aug)
- 1.275M vs 1.31M f'cast, 1.239M prev
- Jobless Claims (Sep)/12
- 196K vs 208K f'cast, 206K prev
- Philly Fed Business Index (Sep)
- 37.8 vs 30.5 f'cast, 47.4 prev
- Philly Fed Prices Paid (Sep)
- 48.60 vs -- f'cast, 40.90 prev
- Building Permits (Aug)
MBS down roughly a quarter point and 10yr up 4.6bps at 4.979
MBS down 3/8ths and 10yr up 7.2bps at 5.005
MBS down 10 ticks (.31) and 10y up 6.6bps at 4.999
MBS down 3/8ths and 10yr up 6bps at 4.993


 MBS Market Alerts